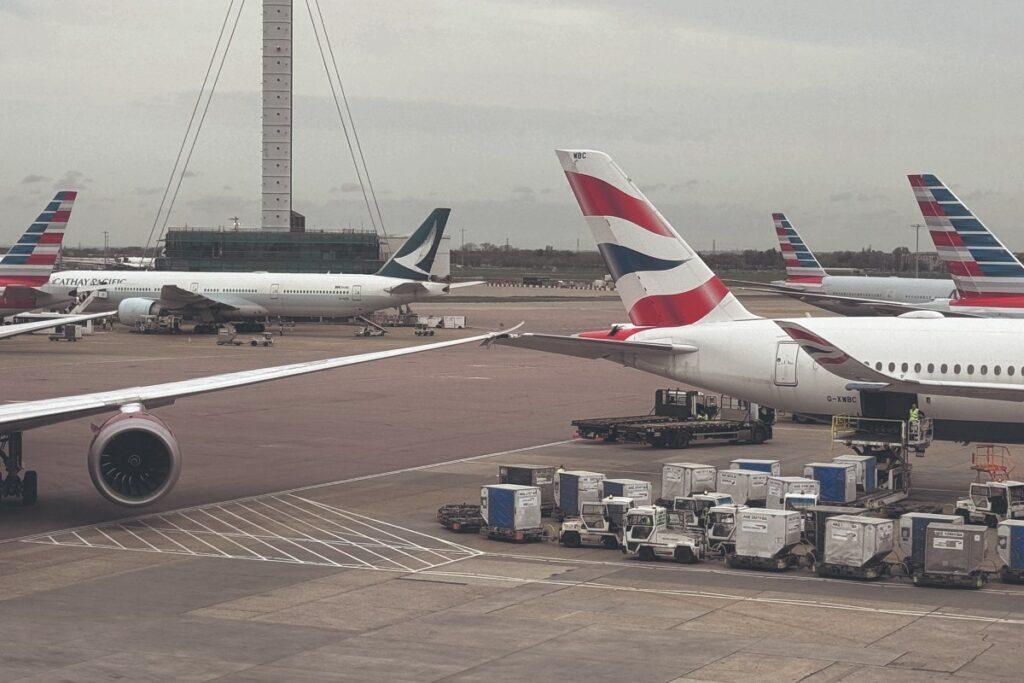
British Airways has successfully contested a tax dispute with HM Revenue and Customs (HMRC) concerning the treatment of accommodation expenses for its cabin crew stationed at London Heathrow Airport. The airline argued that these costs, incurred during consecutive shifts, should not be liable for £5.8 million in income tax and national insurance contributions.
Background of the Dispute
The case centred on whether the costs incurred by cabin crew for overnight stays were considered allowable expenses. British Airways maintained that these accommodations were essential due to the nature of their work, which often involved long hours and irregular schedules. The airline asserted that providing crew members with a place to stay was necessary for operational efficiency and safety, given the demanding nature of their shifts.
HMRC, however, contended that the expenses should be treated as taxable benefits. The dispute raised significant questions about how workplace accommodation is classified and the implications for tax liabilities in the aviation sector.
Outcome of the Legal Challenge
The tribunal ruled in favour of British Airways, concluding that the accommodation costs were indeed legitimate business expenses rather than taxable benefits. This decision has considerable implications for the airline, potentially easing its financial burden and setting a precedent for similar cases within the industry.
This ruling not only benefits British Airways but also provides a clearer understanding of the tax treatment of accommodation expenses for businesses operating in high-demand sectors, particularly those involving shift work. The outcome is likely to encourage other companies facing similar challenges to reassess their tax obligations regarding employee accommodation.
Implications for the Aviation Sector
The ruling is expected to have a ripple effect across the aviation industry, with other airlines and operators taking note of the implications surrounding tax liabilities for accommodation costs. As firms navigate the complexities of tax law, this decision may prompt a broader discussion on the classification of employee expenses and the need for clarity in tax regulations.
As the industry recovers from the impact of recent global disruptions, understanding the financial implications of such rulings will be crucial for airlines aiming to optimise their operational costs while remaining compliant with tax obligations.
More Stories
Pension Savers Reclaim £188 Million After HMRC Overtaxes Withdrawals: A Shocking Oversight
How UK Tax Regulations Influenced the Recent Transfer Window
Revolutionary Inheritance Tax Changes Set to Transform Pension Utilisation in the UK