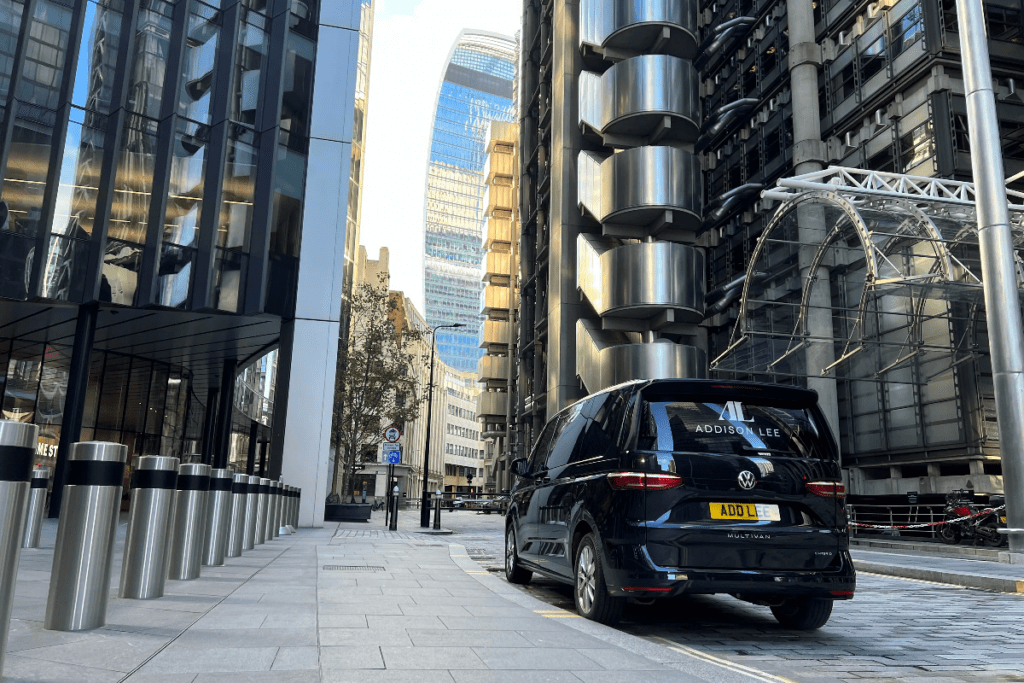
The founder of the esteemed minicab company Addison Lee has been unsuccessful in his attempt to challenge a £20.5 million tax dispute with HM Revenue and Customs (HMRC). His argument centred around the claim that he should be classified as a non-domiciled individual, despite having resided in England for the majority of his life.
Tax Status Under Scrutiny
This case has garnered significant attention as it highlights the complexities surrounding tax residency and domicile status in the UK. The founder’s assertion that he qualifies as a non-dom hinges on his interpretation of tax laws, which allow individuals who are domiciled elsewhere to potentially benefit from certain tax advantages. However, HMRC’s stance has been firm, contending that his long-term residency in England undermines his claims.
The implications of this ruling extend beyond the individual in question, as it raises broader questions about tax compliance and the responsibilities of high-net-worth individuals in the UK. The tax system’s treatment of domicile status has been a contentious issue, often leading to debates about fairness and equity in tax obligations.
Broader Implications for High-Net-Worth Individuals
This case serves as a reminder for high-net-worth individuals regarding the risks associated with domicile claims. HMRC has been increasingly vigilant in scrutinising such assertions, especially in high-profile cases like this one. The outcome not only affects the individual involved but also sets a precedent that could influence similar disputes in the future.
As tax regulations continue to evolve, it is crucial for those in similar financial positions to seek comprehensive legal and financial advice to navigate the complexities of domicile and residency issues. This case underscores the importance of understanding one’s tax obligations, particularly for those with significant assets or complex financial arrangements.
Future Considerations for Tax Compliance
The ongoing scrutiny of tax affairs by HMRC suggests that individuals should be prepared for rigorous assessments of their tax positions. As the founder of Addison Lee grapples with this substantial tax bill, it serves as a cautionary tale for others in the business community. The necessity for transparency and compliance cannot be overstated, especially in an era where tax avoidance is under the microscope.
In conclusion, the outcome of this high-profile tax dispute not only affects the individual concerned but also contributes to the larger conversation about tax policy and compliance in the UK. It reinforces the need for clarity and diligence in tax matters, particularly for those who may be tempted to explore the boundaries of domicile classification.
More Stories
OpenAI’s Unruly AI Displays Behaviour Similar to University Students inebriated on Excessive Alcohol
Burnham Set to Meet Trump as Inflation Soars Amid Ongoing Iran Conflict
UK Economy Poised for Growth Amidst Rising Energy Prices